What Moved the Market
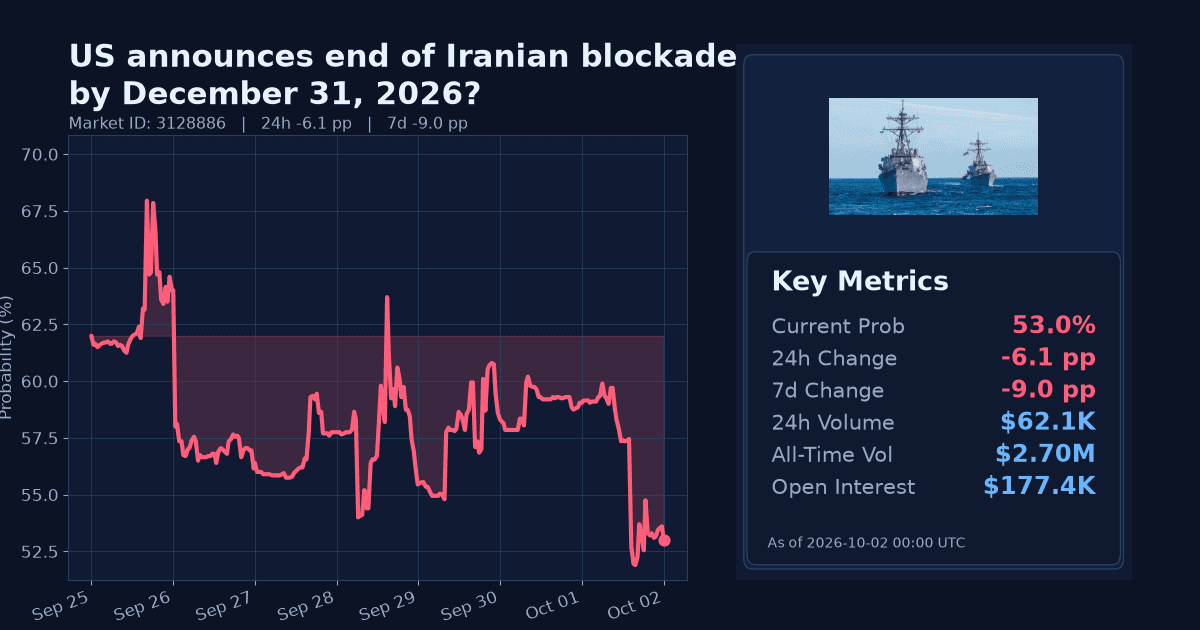
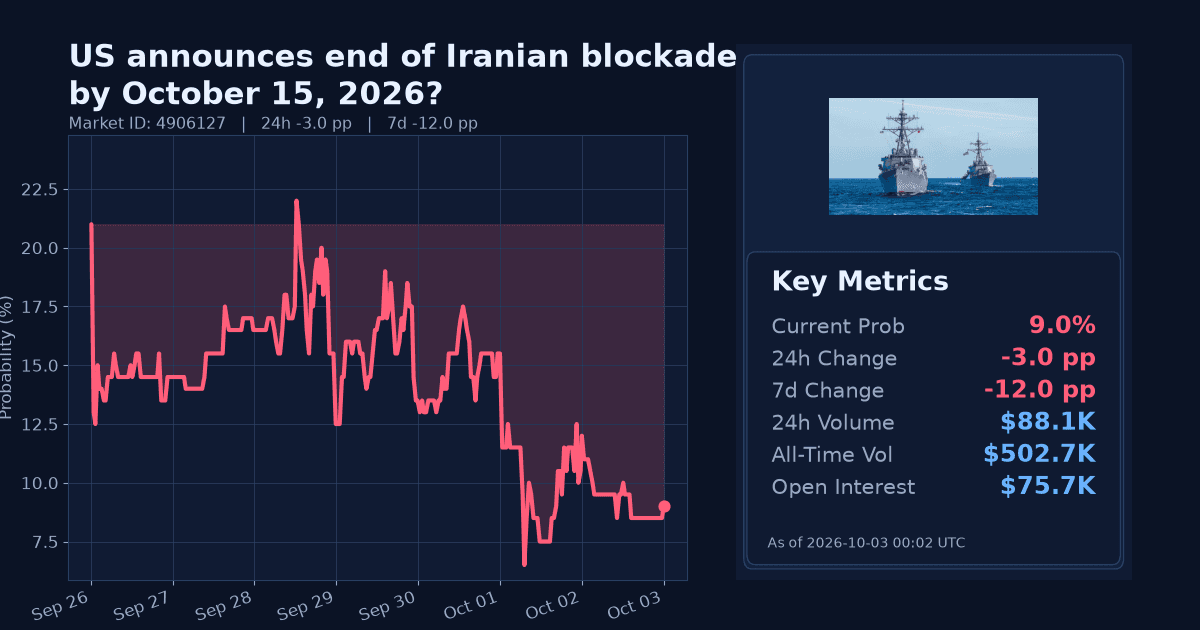
The Polymarket contract “US announces end of Iranian blockade by October 15, 2026?” fell to 9%, down 3 percentage points over 24 hours and 12 points over the past week. The move marks a notable downward repricing in the likelihood of an official US announcement ending or suspending the blockade within the contract window.
This market resolves “Yes” only if an official US government announcement ends, terminates, lifts, or suspends the blockade between market creation (September 24, 2026) and 11:59 PM ET on October 15, 2026. As of October 3, time remaining in the window is limited.
Why It Likely Moved
- Repricing appears driven by the October 2 G7 leaders’ statement, which condemned Iran’s disruptions and called for restoring navigational rights in the Strait of Hormuz, while commending US efforts to ensure free commerce—signaling continued enforcement rather than an imminent lift of the blockade (the Canadian Prime Minister’s Office, 2026-10-02; the UK government, 2026-10-02).
- Markets reacted to the G7’s coordinated release of 100 million barrels from strategic stocks, including a frontloaded diesel component within 20 days, which reduces the need for a policy shift on Iran to alleviate fuel tightness (the UK government, 2026-10-02).
- Additional supply signals—Europe weighing diesel stock releases after US pressure (Ground News/Reuters, 2026-10-02)—reinforce the view that fuel markets will be addressed through inventories rather than de-escalation with Iran.
- The 7-day easing in Brent crude (down ~1.55% to $102.7/bbl) alongside these policy moves supports the notion that immediate energy stress is being managed without altering the blockade.
- With less than two weeks until the October 15 deadline, time decay likely contributed to lower odds in the absence of any qualifying US announcement during the window.
How Strong the Move Is
By the numbers, this is a sharp repricing: -3 percentage points over 24 hours and -12 points over 7 days. The 24-hour z-score of 12.0 is categorized as “extreme,” and the 7-day z-score of 48.0 is likewise “extreme,” indicating the move stands well outside typical recent fluctuations.
Given the consistent weekly decline, this looks like a trend continuation with an extreme daily leg lower, rather than a one-off noise event.
Cross-Market Confirmation
- “US announces end of Iranian blockade by October 31, 2026?” fell to 22% (−3pp 24h, −13pp 7d), confirming a broader downward shift in expectations across adjacent timelines.
- “Kharg Island no longer under Iranian control by October 31?” is 2.1% (+0.1pp 24h), a slight uptick that diverges and likely reflects a different thesis.
- “Kharg Island no longer under Iranian control by December 31?” is 8.0% (+1.0pp 24h, +1.0pp 7d), also a mild divergence, not directly aligned with expectations about US announcements on the blockade.
News & Real-World Context
- On October 2, G7 leaders announced a coordinated release of 100 million barrels from strategic reserves over four months, including a frontloaded diesel release within 20 days, and reaffirmed calls to restore navigational rights in the Strait of Hormuz, commending US efforts there (the Canadian Prime Minister’s Office, 2026-10-02; the UK government, 2026-10-02).
- AP likewise reported that G7 nations agreed to release 100 million barrels, including diesel, to ease fuel prices (AP News, 2026-10-02).
- European officials discussed additional diesel stock releases after US pressure, indicating further non-Iran-policy levers to manage near-term fuel tightness (Ground News/Reuters, 2026-10-02).
- Brent crude stands at about $102.7/bbl, down ~1.55% over 7 days but up ~7.39% over 30 days, suggesting some recent easing against a still-elevated monthly backdrop.
Bottom Line
Traders appear to have discounted the likelihood of a near-term US announcement ending the Iran blockade, as G7 governments publicly backed enforcement while addressing fuel markets through stock releases. With the contract expiring on October 15, time decay and official signals favoring continuity over reversal point to a short-term, deadline-driven repricing rather than a structural shift.
Market Conditions at Time of Writing
- Current Probability: 9%
- 24h Change: -3pp
- 7d Change: -12pp
- Volume (24h, $): 88,101.71
- Open Interest ($): 75,687.36
- Spread (pp): 1.0
- Z-score (24h): 12.0