What Moved the Market
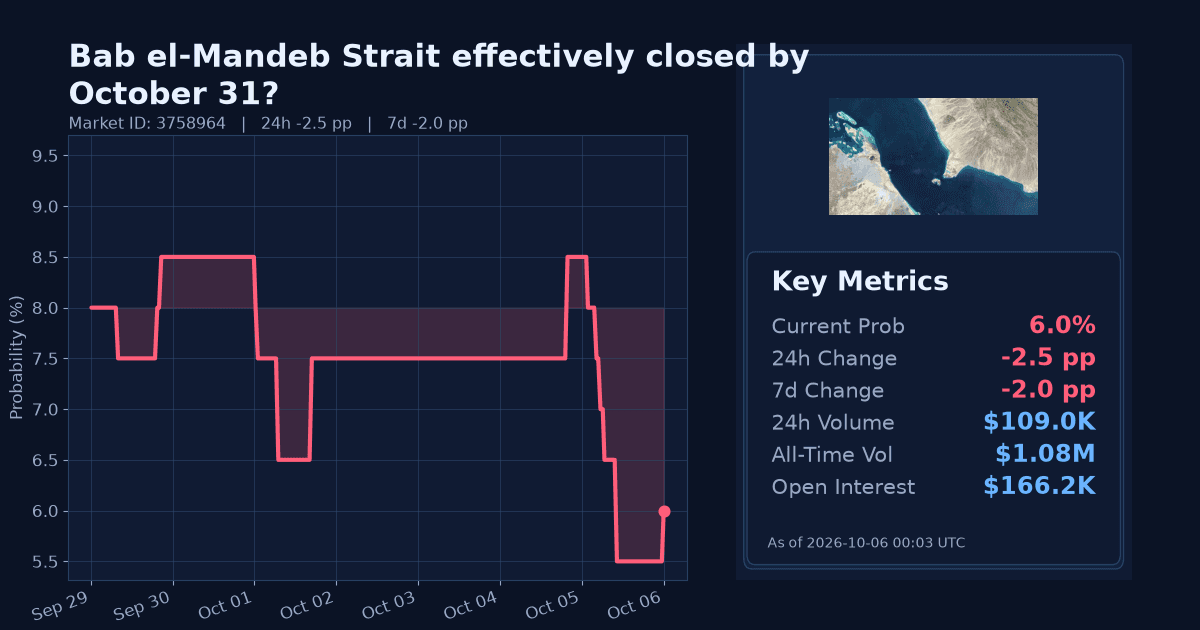
The Polymarket contract on whether the Bab el‑Mandeb Strait will be “effectively closed” by October 31 (defined as IMF PortWatch’s 7‑day moving average of Bab el‑Mandeb transit calls at or below 10 on any date in-window) dropped 2.5 percentage points over the last 24 hours to 6%.
Over the past week the contract is down 2.0pp. The 24h move registers as extreme versus recent trading (z‑score 12.0), with the 7d move also extreme (z‑score 10.0). The market window runs from creation on August 21, 2026 to November 1, 2026; the contract resolves immediately if the threshold is hit before then.
Why It Likely Moved
- Repricing appears driven by the narrowing time remaining to reach the IMF PortWatch threshold (≤10 “Arrivals of Ships” on a 7‑day average) before the November 1 resolution date, lowering the perceived probability mass of a qualifying datapoint emerging in time.
- Markets reacted to easing energy risk signals: Brent crude stands at $100.24/bbl and is down 4.79% over the last 7 days, which can coincide with diminished seaborne supply‑disruption premia and thus lower implied closure odds.
- Cross‑market signals point the same way: the longer‑dated “Bab el‑Mandeb … by December 31?” market also fell over 24h and 7d, suggesting a mild broad repricing lower of closure risk rather than a contract‑specific dislocation.
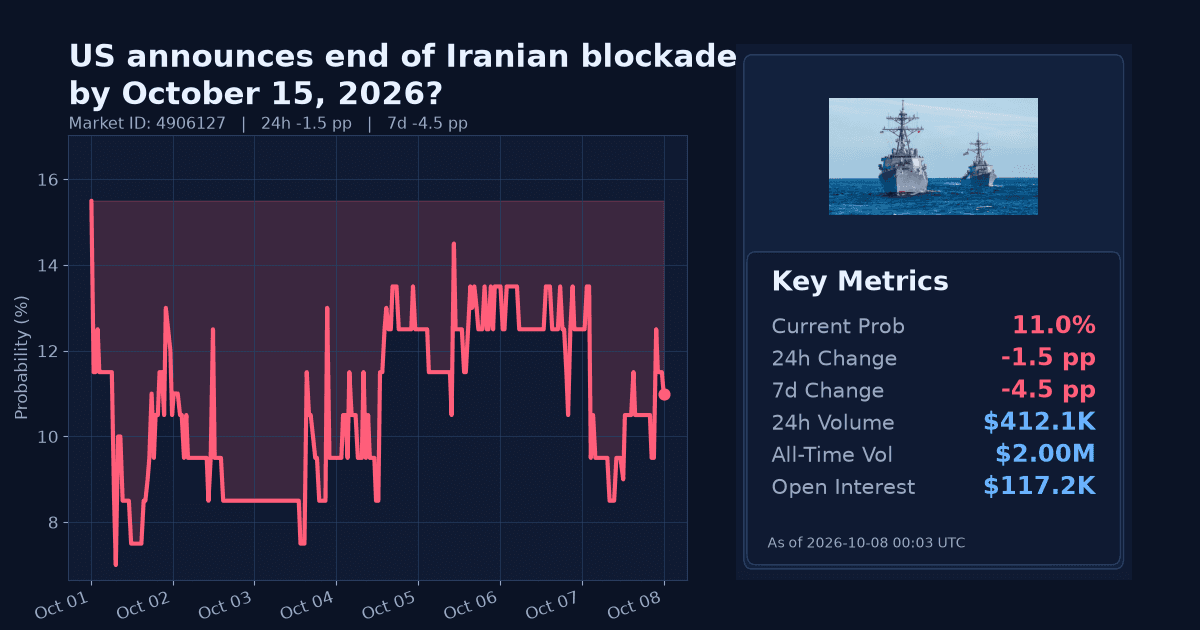
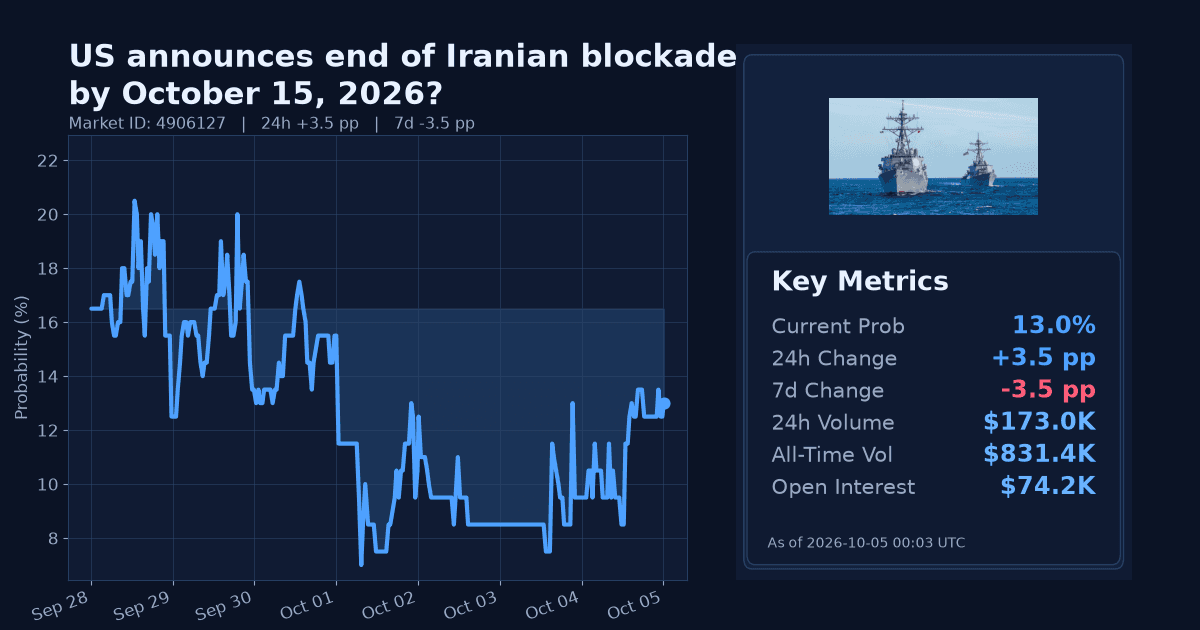
- The repricing follows a 24h uptick in the “US announces end of Iranian blockade by October 31, 2026?” market, which may indicate slightly firmer expectations for near‑term de‑escalation, consistent with lower closure risk here.
- News and official statements provided contain no new, direct government advisories on Red Sea shipping; the absence of fresh official disruption signals in the supplied items may have reduced perceived near‑term closure risk.
How Strong the Move Is
The 24h decline of 2.5pp to 6% is an extreme downside move for this contract by z‑score (12.0). The 7d change (‑2.0pp) is also extreme (z‑score 10.0) but smaller in magnitude, indicating the bulk of repricing occurred in the latest session rather than as a gradual drift.
Given the high 24h volume (~$109k) and a tight spread (1pp), this looks like a significant, high‑conviction markdown rather than illiquid noise. Characterization: a sharp downside spike consistent with time‑window compression.
Cross-Market Confirmation
- Bab el‑Mandeb effectively closed by December 31? Down 1.0pp (24h) and 0.5pp (7d) to 17% — a confirming, smaller parallel decline in longer‑dated closure risk.
- Strait of Hormuz traffic returns to normal by December 31? Down 1.0pp (24h) and 3.0pp (7d) to 19% — this diverges, as reduced odds of “normalization” imply lingering regional disruption even as Bab el‑Mandeb closure odds fall.
- US announces end of Iranian blockade by October 31, 2026? Up 1.0pp (24h) to 22% but down 3.5pp (7d) — the 24h uptick is modest confirmation of improved near‑term de‑escalation sentiment.
News & Real-World Context
- On October 5, 2026, coverage of the Bahrain Formula 1 race relocation cited an “ongoing war with Iran” as the reason the event moved to Malaysia, underscoring regional instability but not indicating a Red Sea closure event Ars Technica (2026‑10‑05).
- Government statements in the provided set do not address Red Sea shipping directly. On October 5, 2026, the UK government delivered a UN Human Rights Council statement on Sudan (2026‑10‑05), and the European Parliament published a written question on Danube Canal issues (2026‑10‑05); these are not Red Sea policy signals.
Macro backdrop: Brent crude at $100.24/bbl is down 4.79% w/w, while the VIX is lower by 3.42% w/w at 15.52, and the USD Index is up 0.94% w/w to 102.15. Together, these data points suggest modestly easier energy risk and calmer market volatility over the week, consistent with trimming tail‑risk probabilities.
Bottom Line
This is an extreme single‑session markdown in the odds of an IMF PortWatch‑defined Bab el‑Mandeb “effective closure” by October 31, likely reflecting time‑window compression and softer energy risk signals, with partial cross‑market confirmation. The move looks tactical and near‑term rather than structural. Subsequent pricing will hinge on any PortWatch prints approaching the ≤10 threshold and any authoritative government advisories.
Market Conditions at Time of Writing
- Current Probability: 6%
- 24h Change: -2.5pp
- 7d Change: -2.0pp
- Volume (24h, $): 108,963.24
- Open Interest ($): 166,155.04
- Spread (pp): 1.0
- Z-score (24h): 12.0